Fun Ways to Teach Kids About Money Through Everyday Life
Children absorb far more from the world around them than from textbooks — and money is no exception. The habits, attitudes, and understanding that children build around finances during their early years tend to stay with them long into adulthood. Yet most schools don’t formally teach personal finance until much later, if at all.
The good news is that everyday life is packed with natural opportunities to introduce children to the basics of money — earning, spending, saving, and making choices. None of it requires special equipment or complicated explanations. You just need to know where to look and how to frame it.
Why Teaching Kids About Money Early Matters
Research consistently shows that financial habits begin forming as early as age seven. Children who grow up understanding the value of money — not just its purchasing power, but the thinking and decision-making behind it — tend to make better financial choices as teenagers and adults.
Early money lessons also build related skills: delayed gratification, goal-setting, basic arithmetic, and the ability to weigh options. These are thinking skills that transfer across every subject in school and every situation in life.
Educators at the best schools in bangalore increasingly recognise that financial literacy begins at home, and that schools can reinforce it through project-based and real-world learning — but the foundation is most naturally built through daily family activities.
Start at the Grocery Store
The weekly grocery run is one of the richest classrooms for money lessons, and it costs nothing extra. Before you leave the house, involve your child in making the shopping list and setting a rough budget. While you’re in the store, talk through your choices aloud.
Why are you choosing the store brand over the branded version? What does ‘price per unit’ mean? Can we get this item on a different day when it’s on offer? These conversations turn a routine errand into a genuine lesson in comparison shopping and value for money.
Age-Specific Grocery Activities
- Ages 4–6: Let them hold the list and check off items. Talk about the difference between things we need and things we want.
- Ages 7–10: Give them a small budget to pick one item of their choice, and let them calculate whether they can afford it.
- Ages 11+: Involve them in comparing prices across brands and working out which option gives the most value.
Run a Pretend Shop at Home
Role-playing a shop at home is one of the most effective money activities for children between four and nine. Set up a small ‘shop’ using items from around the house, label them with prices, and give your child a set amount of pretend money to spend.
Switch roles regularly — sometimes they’re the customer, sometimes the shopkeeper. As the shopkeeper, they learn to calculate totals and make change. As the customer, they make spending decisions within a budget. Both perspectives are valuable.
- Start with round numbers and simple prices to build confidence.
- Introduce coins before notes so children understand smaller denominations.
- Add a ‘sale’ day where selected items are discounted and let children work out the savings.
- As they get older, introduce receipts and written totals.
Give Pocket Money With Purpose
Pocket money, when structured thoughtfully, is one of the most powerful tools for teaching real financial decision-making. The key is giving children genuine autonomy over how they spend it — while also holding them to the natural consequences of those choices.
If a child spends all their pocket money in the first two days and wants more mid-week, resist the urge to top it up. Running out of money is an excellent and low-stakes lesson in budgeting. When children experience the consequence directly, they remember it.
How to Structure Pocket Money Effectively
- Give a consistent amount on a consistent day each week or month
- Keep the amount age-appropriate — enough to make real choices, not so much that decisions carry no weight
- Avoid linking pocket money entirely to chores — this blurs the difference between allowance and employment
- Let them make mistakes and talk through what they'd do differently next time
Turn Goal-Setting Into a Visual Game
Children are natural goal-setters when the goal is something they actually want. If your child has been asking for a particular toy, book, or experience, use it as an opportunity to build a savings goal together.
Create a simple chart — a thermometer, a ladder, or even a drawing of the item with sections to colour in as savings grow. Each time they add to their savings jar, they colour in the next section. The visual progress is highly motivating for children and teaches the concept of working toward something over time.
This kind of goal-oriented thinking is something the schools in sarjapur road actively nurture in their students — connecting short-term effort to long-term reward is a mindset that serves children well in academics and in life.
Use Everyday Moments to Explain Real-World Money Concepts
You don’t need a lesson plan to teach money literacy — you just need to narrate the financial decisions you’re already making. When you’re at the petrol station, the ATM, or paying a bill online, involve your child in what’s happening. Brief, honest explanations go a long way.
| Everyday Moment | Money Concept to Introduce | Age Range |
|---|---|---|
| Grocery shopping | Needs vs wants, budgeting, comparison | 4–12 |
| ATM visit | Banks, savings, where money comes from | 5–10 |
| Paying bills online | Fixed expenses, planning ahead | 8–12 |
| Restaurant meal | Budgeting, tipping, value for money | 7–12 |
| Receiving birthday money | Saving goals, spending choices, giving | 4–12 |
| Seeing an advertisement | Marketing, persuasion, impulse buying | 6–12 |
Key Takeaways
- Financial habits form as early as age seven — everyday activities are the best classroom
- Grocery shopping, pretend play, and pocket money all teach real money concepts without any special resources
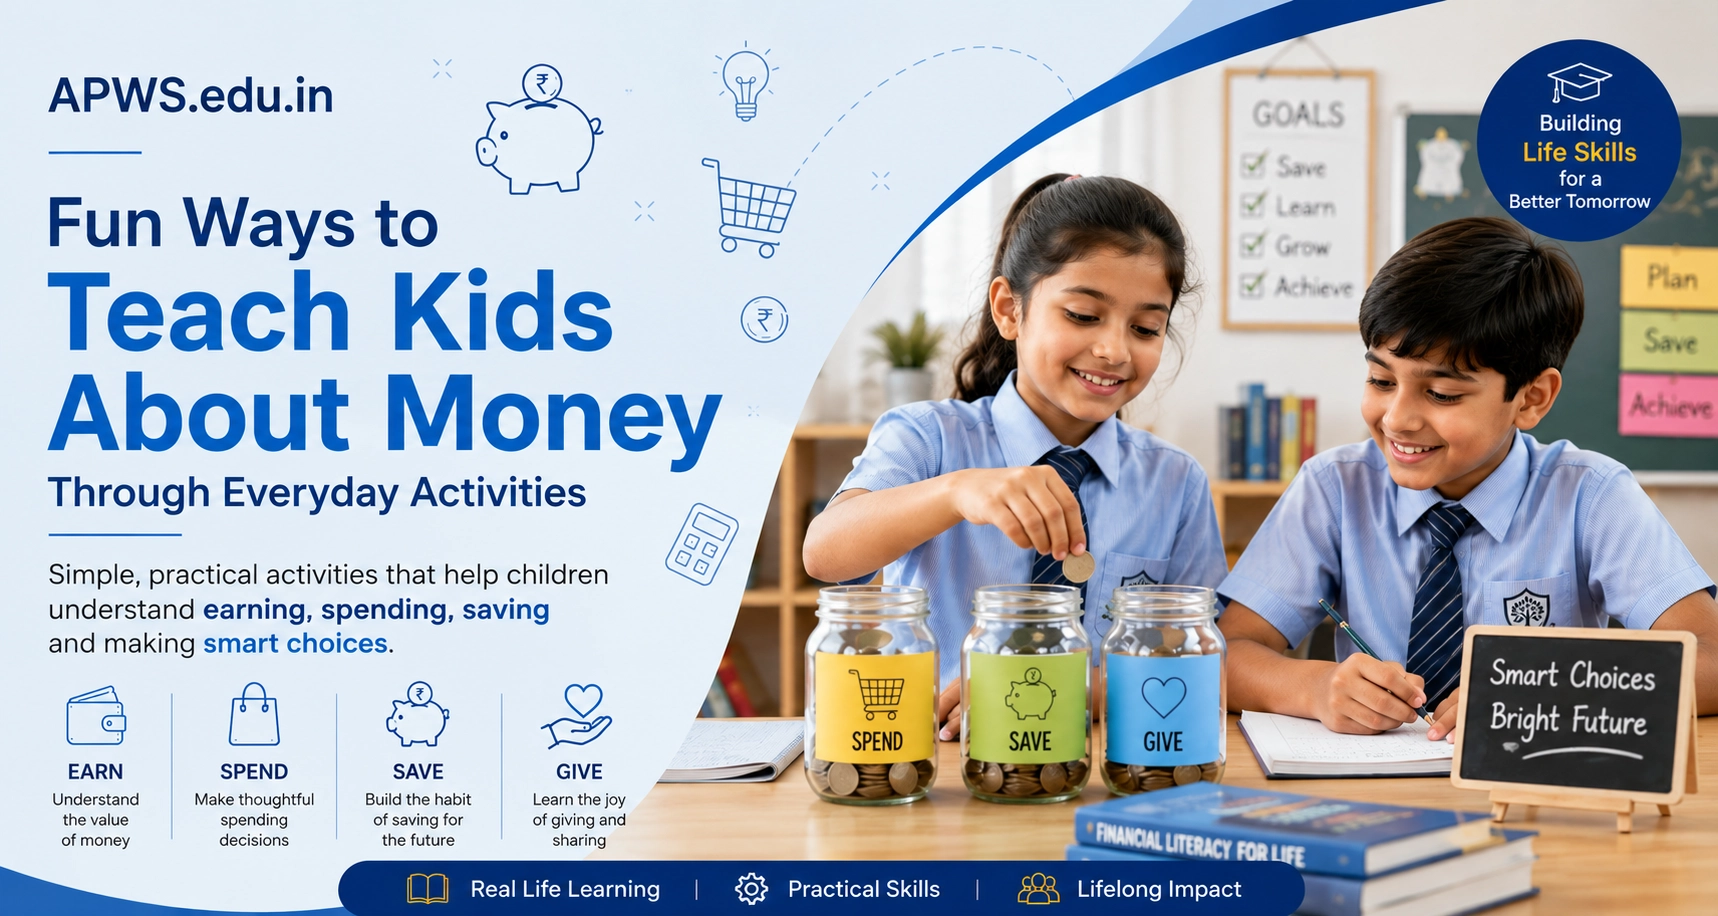
- The three-jar system (spend, save, give) introduces allocation thinking to young children
- Visual savings goals keep children motivated and teach delayed gratification
- Narrating your own financial decisions gives children a model to learn from
Conclusion
Teaching children about money doesn’t require a formal curriculum or a specific age to begin. The everyday activities of family life — shopping, saving, spending, and choosing — are already full of financial lessons waiting to be unlocked. Parents who take the time to make these moments intentional give their children a genuine head start. And schools, particularly the top cbse schools in bangalore that prioritise holistic development, build on this foundation to produce students who are as financially thoughtful as they are academically capable.
Start small, stay consistent, and let real life do the teaching.
FAQs
1. At what age should I start teaching my child about money?
You can introduce basic concepts like ‘needs vs wants’ and coin recognition as early as age three or four. More structured lessons like pocket money and savings goals work well from age six onwards.
2. How much pocket money should I give my child?
There’s no universal answer, but a common guideline is ₹10–20 per year of age per week. The amount matters less than the consistency and the autonomy you give them over it.
3. Is it a good idea to pay children for doing chores?
It can be, but consider separating core household responsibilities (unpaid, as part of family contribution) from optional extra tasks (paid). This keeps the relationship between work and money realistic.
4. What if my child spends all their money immediately?
Let it happen, then have a conversation about it. Running out of money is one of the most effective lessons in budgeting — far more memorable than any explanation.
5. How do I explain credit cards and loans to children?
For younger children, describe a credit card as ‘borrowing money you have to pay back later, plus a bit extra.’ As they get older, introduce the idea of interest and why borrowing can be expensive.
6. Should children be told how much their parents earn?
This depends on the family and the child’s age, but sharing a general sense of income and expenses helps children understand household financial decisions rather than seeing money as mysterious or unlimited.
7. Are there apps that help teach children about money?
Yes — apps like Spriggy, Greenlight, and BusyKid use digital pocket money accounts with savings goals built in. They’re particularly engaging for older children aged eight and above.
8. How do I teach my child the difference between needs and wants?
Start with concrete examples: food and shelter are needs; toys and sweets are usually wants. When shopping, ask your child to categorise items before you buy them — the discussion itself is the lesson.